Quick Answer
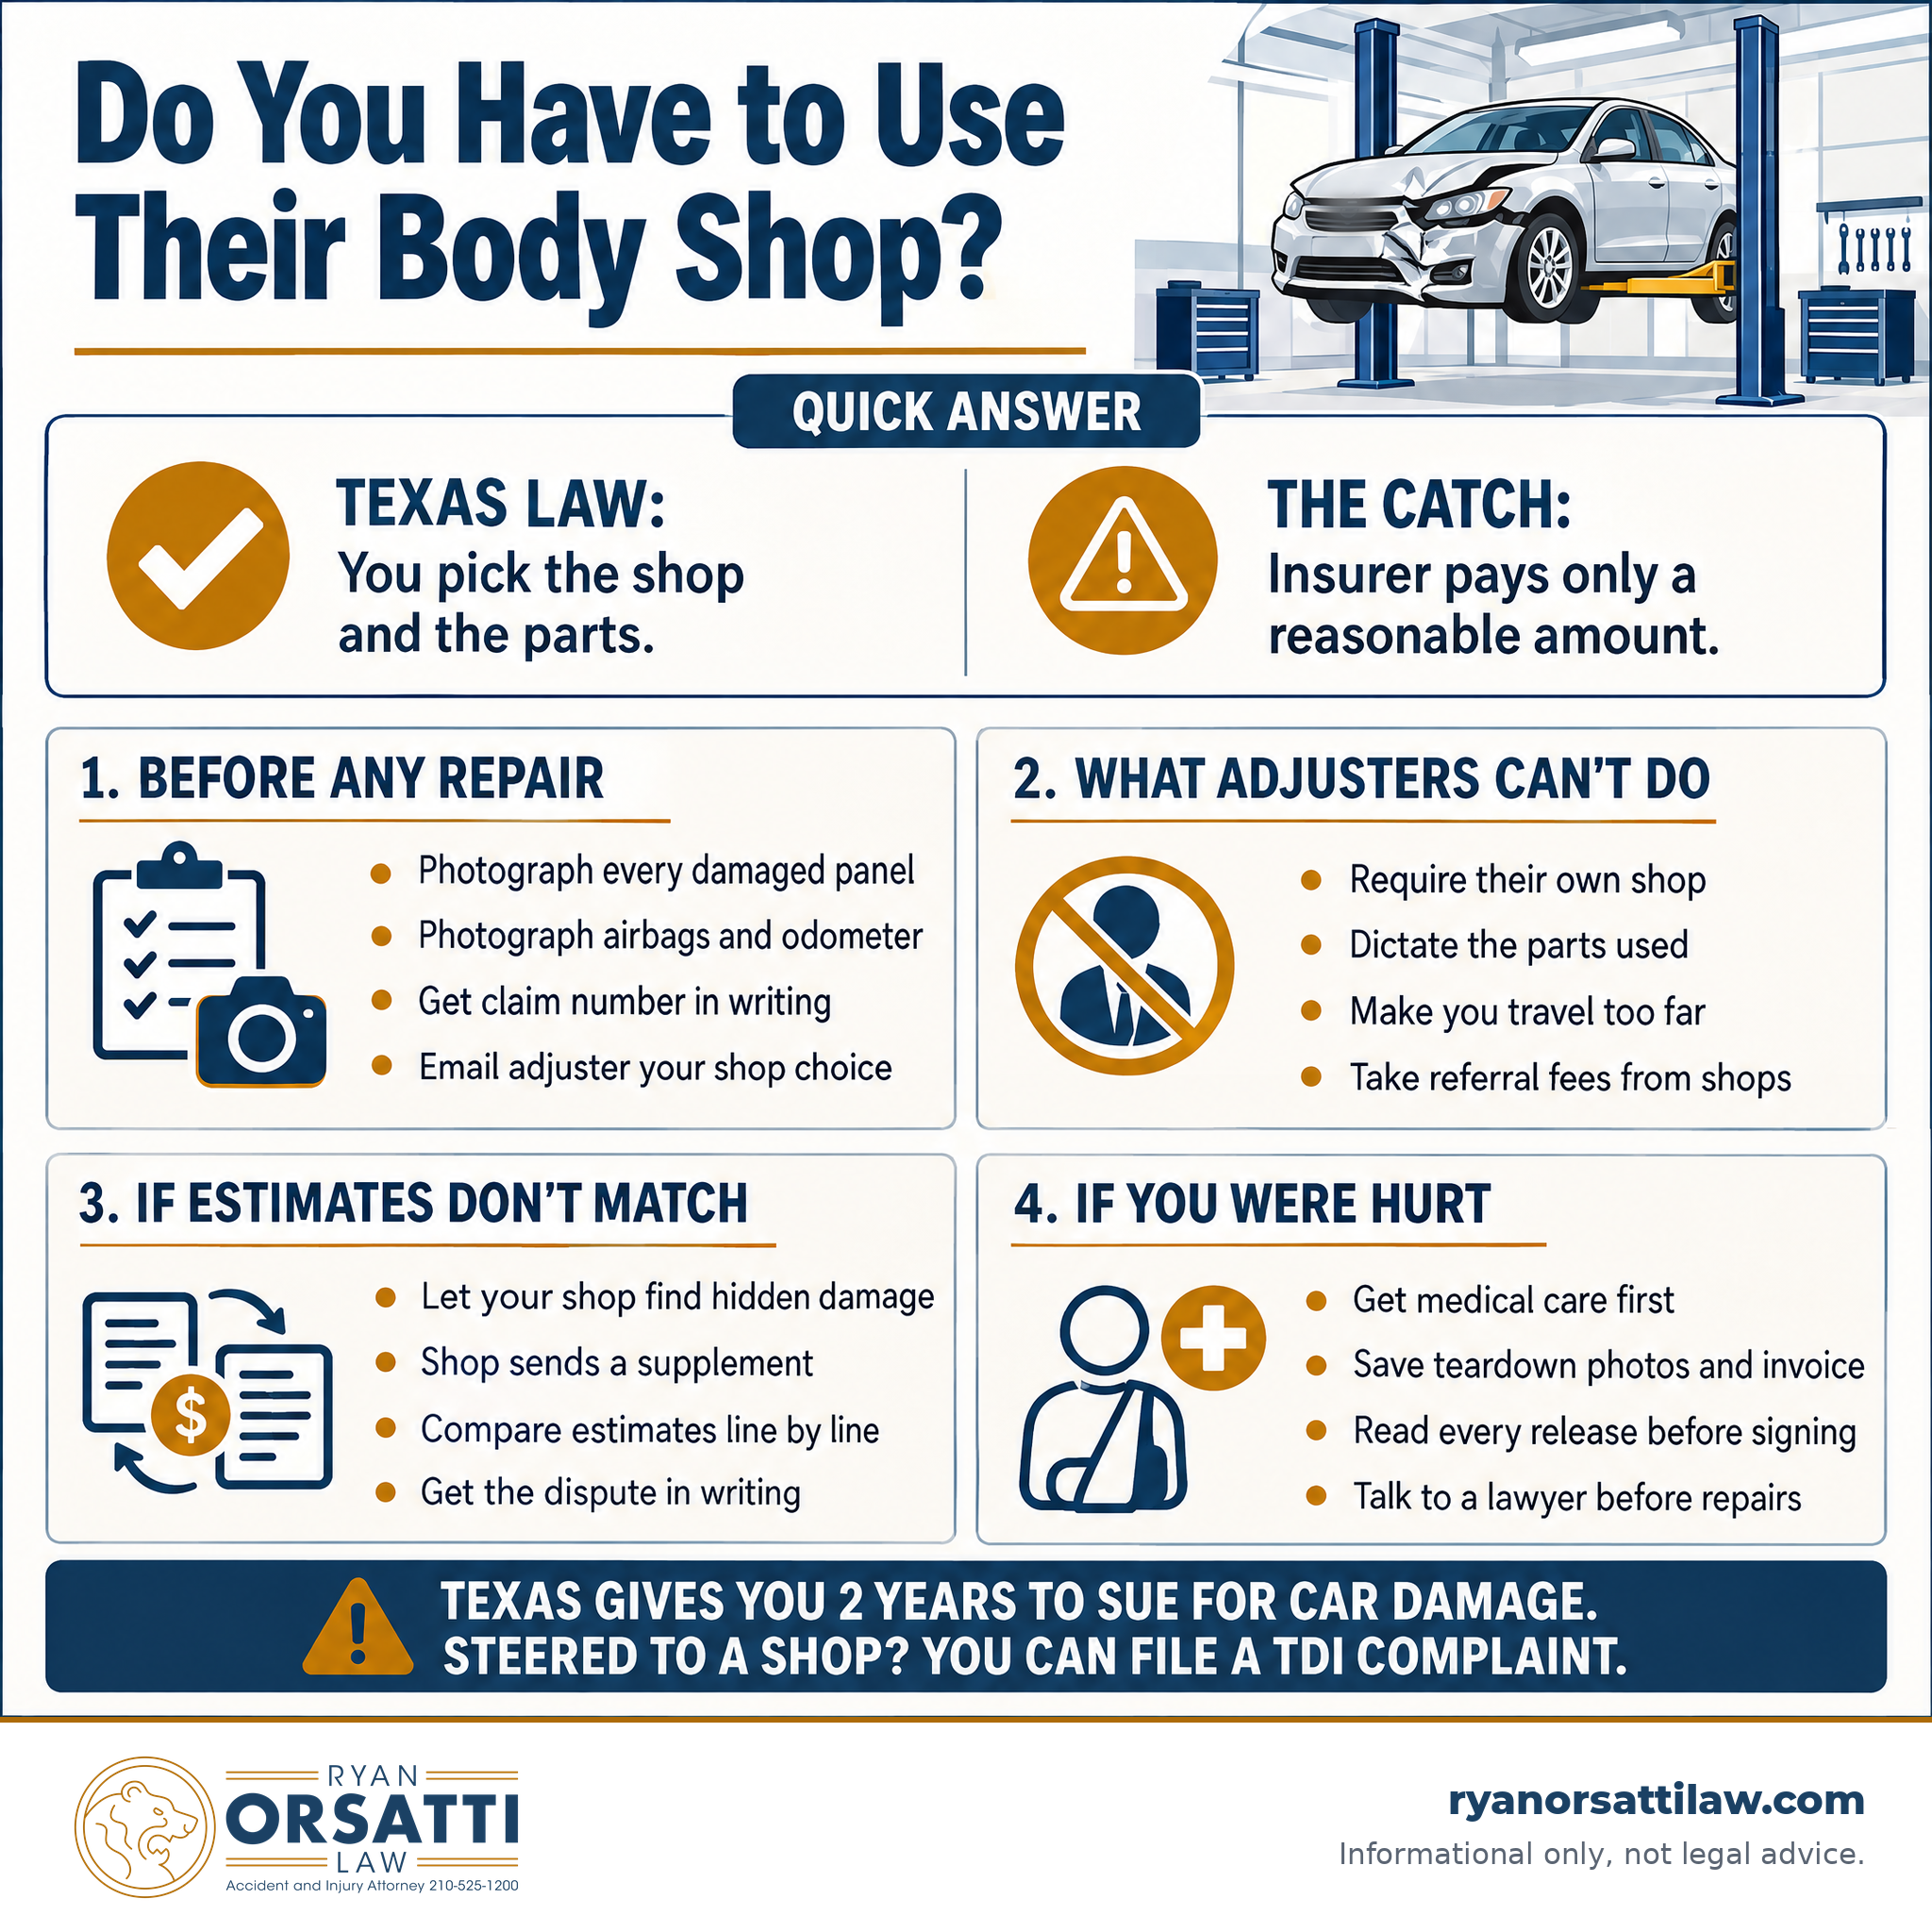
- Do you have to use the insurance company’s body shop in Texas? No. You can take your car to any repair shop you choose.
- Texas Insurance Code Sec. 1952.301 protects that choice on a claim with your own insurer and on a claim against the at-fault driver’s insurer.
- An adjuster may not tell you that your repair is covered only at a shop on the insurer’s preferred list.
- The catch: the insurer only has to pay a reasonable amount for repairs and parts, so the real fight is usually over the estimate, not the shop.
Key Takeaways
- Texas has barred auto insurers from steering you to a particular repair shop since April 1, 2007, when Subchapter G of Insurance Code Chapter 1952 took effect.
- The insurer also cannot dictate the brand, type, age, vendor, or condition of the parts used on a covered repair.
- An insurer cannot make you travel an unreasonable distance to get your car repaired.
- When you report a vehicle damage claim in writing, the insurer must send written notice of your repair rights within 3 business days.
- Texas gives you two years from the crash to file a lawsuit over damage to your car.
- If you were hurt, photograph the damage before any shop touches the car. The repair file often becomes evidence in the injury claim.
If the other driver’s insurer is pushing you toward its shop while you are also dealing with an injury, Ryan Orsatti Law can help you sort out both sides of the claim. We are a San Antonio personal injury firm that has represented injured Texans for more than a decade, and the first consultation is free.
Can the Insurance Company Make You Use Its Body Shop in Texas?
No. Under Texas Insurance Code Sec. 1952.301(a), an auto insurer may not limit your coverage by keeping you from selecting the repair person or facility that fixes your car. The same rule bars the insurer from specifying the brand, type, kind, age, vendor, supplier, or condition of the parts.
The law covers you even when you are not the policyholder. Under Sec. 1952.301(b), the at-fault driver’s insurer cannot require you, as a third-party claimant (someone claiming against another person’s policy), to use a particular shop or particular parts when it settles your property damage claim.
Sec. 1952.302 adds three more limits. They apply to the insurer, its employees and agents, adjusters, and companies that employ adjusters:
- No referral fees or gratuities for sending you to a repair shop.
- No stating or suggesting, in person or in writing, that your repair is covered only at a specific shop or a shop on the insurer’s preferred list.
- No requiring you to travel an unreasonable distance to get the damage repaired.
One wrinkle is worth knowing. Sec. 1952.301(a) opens with “except as provided by rules adopted by the commissioner,” and Sec. 1952.307 says any such limit must be shown clearly on the face of the policy, with your written consent after oral and written notice when you buy it. In plain English, a policy that restricts your shop choice would have to say so up front, and you would have had to sign off. If you never agreed to that, the standard rule applies.
Attorney Insight: Steering rarely sounds like an order. What injured Texans usually tell us they heard is softer: the claim will move faster at our shop, we can only stand behind repairs done in our network, or your shop’s rates may not be fully covered. None of that changes your right to choose. Answer with one short email that names your shop and asks the adjuster to send the estimate there. A written record ends most of these conversations.
Why Do Insurance Companies Have Preferred Body Shops?
Insurance companies have preferred body shops because those shops sign contracts with the insurer, often called direct repair programs. Texas law expects these deals. Sec. 1952.303 describes agreements where a shop gives the insurer discounts on parts or labor in exchange for referrals, and it says those agreements may not reduce your coverage.
A network shop can be convenient, and approval may move faster. The trade-off is simple. A shop that depends on one insurer for a steady flow of work has two customers on your car. The Texas Department of Insurance (TDI) has warned insurers about steering and about artificially low labor and parts rates. In Bulletin B-0026-11, TDI said a notice suggesting you will pay extra costs for choosing a non-preferred shop may conflict with the law because it discourages that choice.
Which Situation Fits You?
Your rights to pick the shop are the same either way. What changes is who pays, whether you owe a deductible, and which deadlines the insurer has to meet.
- The other driver caused the crash and has insurance. You file a third-party claim on their liability coverage. You owe no deductible. Texas requires at least $25,000 in property damage liability coverage per collision under Transportation Code Sec. 601.072, and many drivers carry more.
- You use your own collision coverage. This makes sense when fault is disputed, the other driver has no insurance, or their insurer is dragging its feet. You pay your deductible, and your insurer can later try to recover it from the at-fault driver. The prompt-payment deadlines in Insurance Code Chapter 542 apply to claims on your own policy.
- Your car is a total loss. Shop choice matters less here. The dispute becomes the car’s value, any loan balance, and how long you were without a vehicle.
| Question | Claim on your own policy | Claim against the at-fault driver’s insurer |
|---|---|---|
| Can they require their shop? | No (Ins. Code Secs. 1952.301(a), 1952.302) | No (Ins. Code Sec. 1952.301(b)) |
| Can they dictate the parts? | No, unless your policy disclosed a limit you signed | No |
| Notice of your repair rights | Written notice within 3 business days of a written claim | Same notice rule |
| Payment deadlines | Acknowledge in 15 days, decide in 15 business days, pay in 5 business days | Chapter 542 deadlines do not apply |
| What they must pay | A reasonable amount for repairs and parts, minus your deductible | Reasonable repair cost, up to the policy limit ($25,000 minimum) |
| Deadline to sue | Set by your policy and contract law | 2 years from the crash (Civ. Prac. & Rem. Code Sec. 16.003) |
What Happens If the Insurance Estimate Is Lower Than the Body Shop’s?
When the insurance estimate is lower than your shop’s, the shop and the insurer negotiate the difference, and you should stay in the loop. The insurer only owes a reasonable amount for the repair. Many gaps close on their own once the shop tears the car down, finds hidden damage, and sends the insurer a supplement (an add-on estimate for damage found after disassembly).
A few rules work in your favor here:
- Under Sec. 1952.304, the insurer cannot stop your shop from telling you what parts were used, who made them, where they came from, and what the shop charged the insurer for parts and labor.
- TDI’s Bulletin B-0026-11 says paying an amount that is not enough to make the repairs needed for the manufacturer to honor the vehicle warranty is an unfair claim settlement practice.
- Your own policy may include an appraisal clause, which lets either side ask a neutral process to set the repair amount. Check your policy language.
If the gap is large and nobody will move, ask the shop to put its position in writing with photos. That document is what you will send to TDI, or to a lawyer, if it comes to that. Our post on what to do when the at-fault driver’s insurance won’t cover full repair costs walks through the next steps.
What to Do Before Your Car Goes to Any Body Shop: 7 Steps
These steps protect your repair claim and any injury claim at the same time. For more detail on the photos and paperwork, see our guide to documenting property damage after a Texas car accident.
- Photograph every damaged panel, the bumpers, the interior, any deployed airbags, and the odometer before anyone moves or repairs the car.
- Get the claim number and the adjuster’s name and direct contact information in writing.
- Pick your shop, then tell the adjuster by email where the car is going, so the request is on the record.
- Ask for the written notice of your repair rights if you have not received it.
- Get both estimates, yours and the insurer’s, and compare them line by line, including whether each part is new from the manufacturer or aftermarket.
- Move the car out of the tow yard quickly and save every receipt for towing, storage, and rental. Storage charges usually keep running while the car sits.
- Read every check, release, and authorization before you sign. A property damage release should say it covers property damage only.
Attorney Insight: The repair file is injury evidence, whether you like it or not. In matters we handle, the defense routinely points to a low repair bill to argue a minor impact that could not have hurt anyone. The answer is usually sitting in the shop’s own paperwork: teardown photos, the supplement, and the final invoice showing bumper reinforcement or frame work you could not see from the outside. Before you pick up your car, ask the shop for copies of all three.
Can You Get a Rental Car While Your Car Is in the Shop?
On a claim against the at-fault driver, you can usually recover the reasonable cost of a rental, or the value of the lost use of your car, for a reasonable repair period. Texas courts call this loss of use. In J&D Towing, LLC v. American Alternative Insurance Corp. (Tex. 2016), the Texas Supreme Court held that loss-of-use damages are recoverable even when a vehicle is totally destroyed, and noted Texas already allowed them when property is damaged but repairable.
On your own policy, a rental depends on whether you bought rental reimbursement coverage. We cover the fine print, including taxes and fees, in our post on whether loss of use in Texas covers rental car taxes and fees.
How Do You Report an Insurer That Steers You to Its Shop?
You can file a written, documented complaint with TDI. Sec. 1952.306 lets a policyholder, a third-party claimant, or the repair shop itself complain about a violation of these repair rules. TDI’s help line is 1-800-252-3439.
Your complaint is only as strong as your record. Write down who told you to use their shop, the date, and the exact words. Save texts and emails, and keep any letter that says you will pay extra for using your own shop.
Why Injured Texans Bring the Repair File to Their Lawyer
A body shop dispute can look like a small fight about labor rates, but in an injury case it is part of the evidence. A lawyer reviewing the claim looks at who pressured the repair decision, whether the estimate reflects the real damage, whether any release signed so far reaches beyond property damage, and whether the photos and invoices support the force of the impact. Ryan Orsatti Law reviews these files for people hurt in San Antonio car accidents, truck accidents, motorcycle crashes, and pedestrian collisions across Bexar County and the rest of Texas, and we look at the property damage file and the injury claim together. We work on a contingency fee, so you owe no attorney’s fee unless we recover for you.
Frequently Asked Questions
Can my insurance company make me use their body shop in Texas?
No. Texas Insurance Code Sec. 1952.301 says an auto insurer may not limit your coverage by restricting your choice of repair shop, and Sec. 1952.302 bars adjusters from saying your repair is covered only at a preferred shop. A separate provision protects you when you claim against the other driver’s insurer. The insurer still only has to pay a reasonable amount for the repair.
Why do insurance companies have preferred body shops?
Insurers sign contracts with preferred shops, often called direct repair programs. Texas law describes deals where a shop gives the insurer discounts on parts or labor in exchange for referrals. Those deals may not reduce your coverage. A network shop can be convenient, but it also depends on the insurer for business, so compare its estimate with one from a shop you choose.
What happens if the insurance estimate is lower than the body shop estimate?
The shop and the insurer usually negotiate, and many gaps close once the shop tears the car down and sends a supplement for hidden damage. The insurer must pay a reasonable amount for the repair. If it refuses, get the shop’s position in writing with photos, check your policy for an appraisal clause, and consider a complaint to the Texas Department of Insurance.
Can the insurance company make me drive far to a shop?
No. Texas Insurance Code Sec. 1952.302 bars an insurer, its adjusters, and its agents from restricting your choice of shop by requiring you to travel an unreasonable distance to get the damage repaired. That protection covers both policyholders and people claiming against another driver’s policy. If an adjuster insists on a faraway shop, ask for the request in writing and keep a copy.
How long do I have to file a property damage claim in Texas?
Texas Civil Practice and Remedies Code Sec. 16.003 gives you two years from the date of the crash to file a lawsuit for damage to your property, and the same two-year period applies to personal injury. Report the claim to the insurer right away, though. Evidence fades fast, cars get repaired or salvaged, and waiting rarely helps you on either claim.
Should I wait to talk to a lawyer until my car is fixed?
No. If you were hurt, talk to a lawyer before the car is repaired or released to salvage, because the damage itself is evidence of how hard you were hit. Get medical care first, save photos, and do not sign a release until you know exactly what it covers. A free consultation costs nothing and can keep a property damage decision from hurting the injury claim.
Source Notes
- Texas Insurance Code Chapter 1952, Subchapter G, Secs. 1952.301 to 1952.307 (repair of motor vehicles): statutes.capitol.texas.gov
- 28 Texas Administrative Code Sec. 5.501 (written notice of repair rights, within three business days of a written claim): tdi.texas.gov
- Texas Insurance Code Sec. 542.055 (acknowledgment within 15 days): statutes.capitol.texas.gov
- Texas Insurance Code Sec. 542.056 (decision within 15 business days): statutes.capitol.texas.gov
- Texas Insurance Code Sec. 542.057 (payment within 5 business days): statutes.capitol.texas.gov
- Texas Transportation Code Sec. 601.072 (minimum liability coverage, including $25,000 property damage): statutes.capitol.texas.gov
- Texas Civil Practice and Remedies Code Sec. 16.003 (two-year limitations period): statutes.capitol.texas.gov
- Texas Department of Insurance, Bulletin B-0026-11 (steering and repair reimbursement): tdi.texas.gov
- Texas Department of Insurance, Consumer Bill of Rights, Personal Automobile Insurance (right to choose the repair shop and parts, TDI help line): tdi.texas.gov
- Consumer Bill of Rights, Personal Automobile Insurance, as published in the Texas Register (repair notice timing): sos.state.tx.us
- J&D Towing, LLC v. American Alternative Insurance Corp., No. 14-0574 (Tex. Jan. 8, 2016): txcourts.gov
Ryan Orsatti Law
4634 De Zavala Rd, San Antonio, TX 78249
Phone: 210-525-1200
ryanorsattilaw.com
This blog is for informational purposes only, not legal advice. Reading it does not create an attorney-client relationship. Past results do not guarantee future results.
Hurt in an accident in San Antonio? Learn how a San Antonio personal injury lawyer can help with your claim. Call 210-525-1200 or request a free consultation.
The firm works on a contingency fee. You pay nothing unless the firm recovers money for you, and that covers case expenses as well as the fee: if there is no recovery, you owe no attorney's fee and no case expenses. Ask for the fee agreement and read the fee and expense section before you sign anything.
Related San Antonio legal resources
Primary legal and public-data sources
- Texas Civil Practice and Remedies Code Chapter 16: limitations
- Texas Civil Practice and Remedies Code Chapter 33: proportionate responsibility
Ryan Orsatti Law
4634 De Zavala Road, San Antonio, TX 78249
General reference links. Consult each source for its current text.